XL Bully Insurance in the UK: What the Law Requires Now and Who Will Cover Your Dog
XL bully owners no longer need liability insurance by law, but the dog still needs cover. The rules in England, Wales, Scotland and Northern Ireland, which insurers will cover an XL bully's vet bills, and what drives the cost. Checked October 2026.
Published 31 October 2026
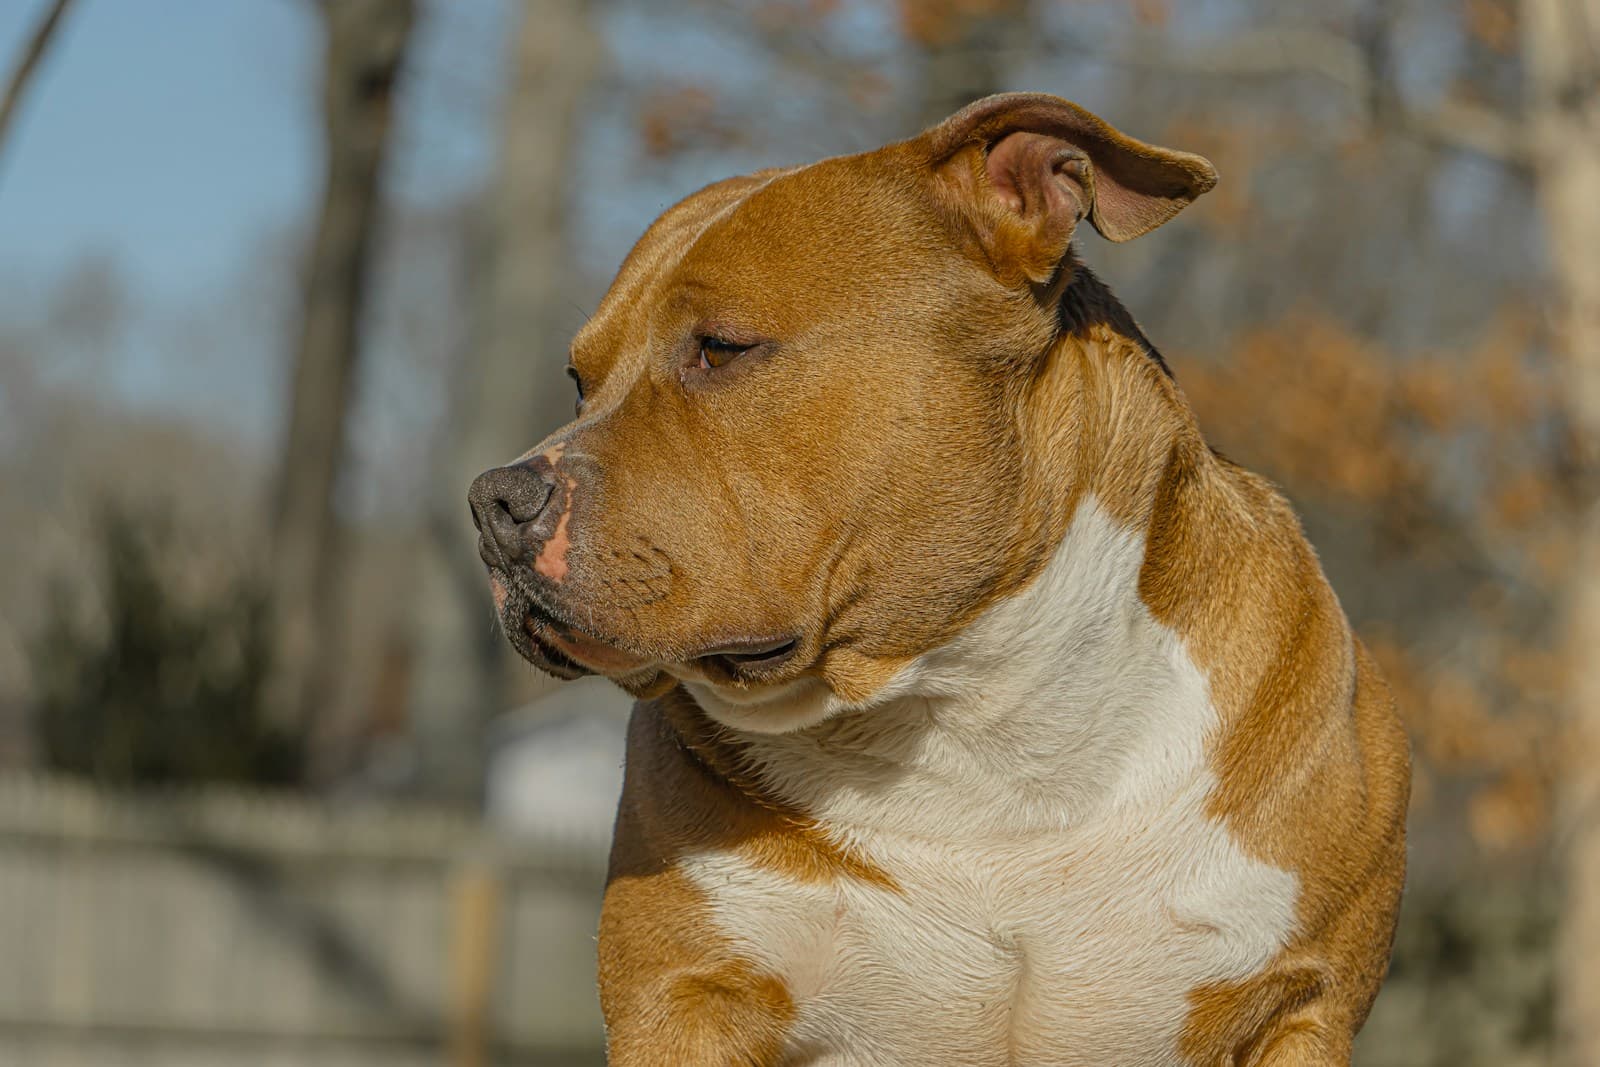
If you searched for XL bully insurance because you thought the law still made you buy it, there is good news and a catch. The legal requirement for third-party liability insurance ended on 1 July 2026. The catch is that the dog still needs cover, and very few insurers will now give it.
This guide covers what the law says today in each part of the UK, the difference between liability cover and vet fee cover, which insurers will take an XL bully, and what decides the price. For the rest of the exemption rules, including the new rule on children from 1 November 2026, see our guide to the XL bully rules.
The law changed on 1 July 2026
Until 30 June 2026, every Certificate of Exemption came with a condition: the dog had to be covered by third-party public liability insurance for its whole life. That condition has now gone in every part of the UK, with one difference in Scotland.
- England and Wales. GOV.UK now says: "You do not need third party public liability insurance for banned breed dogs, including XL Bully dogs." The change came in through the Dangerous Dogs (Exemption Schemes) (England and Wales) (Amendment) Order 2026.
- Scotland. You no longer need to take out or renew liability insurance from 1 July 2026. But if you took out a policy before that date, the law says you must keep it in force until it expires. mygov.scot puts it more simply: if you already have insurance, let the policy run until it ends.
- Northern Ireland. nidirect says a policy had to be in place up to and including 30 June 2026, and not after.
Every other condition still applies. The dog must be neutered, muzzled and on a lead in public, kept at the certificate holder's address and kept securely. Breaking those conditions costs the dog its exemption. Losing insurance no longer does.
Liability cover and vet fee cover are different things
A lot of confusion about XL bully insurance comes from two products sharing one name.
Third-party liability insurance pays out when your dog injures someone or damages their property and a court finds you legally responsible. Agria's policy document describes it this way: it pays the compensation and costs a court awards, plus the legal costs of defending the claim. This was the cover the law used to require.
Pet insurance, which is what most people mean by health insurance for a dog, pays your dog's own vet bills when it is ill or injured. The law never required it, and it is the cover most owners actually claim on. UK insurers paid £1.23 billion in pet claims in 2024, with an average claim of £685, according to the Association of British Insurers.
Many pet insurance policies, including Agria's and ManyPets', also have a liability section. For an XL bully, that section is where the exclusions bite, as you will see below.
Should you still have liability cover?
The legal duty has gone, but the risk has not. If your dog injures someone or damages their property, you can still be held legally responsible, and without insurance the compensation and legal costs are yours to pay. For a large, powerful dog under this much public scrutiny, that is a real risk rather than a remote one.
The difficulty is finding it. The main routes owners used have closed:
- Dogs Trust removed third-party public liability insurance from its Companion Club from 1 July 2026. Members who renewed up to and including 30 June 2026 keep it for a further 12 months from their renewal date. Anyone renewing from 1 July 2026 does not get it.
- Everypaw says it will no longer offer third-party liability cover on XL bully policies from the next renewal.
- Petplan says it can only offer liability cover for XL bully type dogs in very limited circumstances.
- Agria lists third-party public liability under what its XL bully cover does not include.
What is left is worth checking yourself. Some home insurance policies include liability for pets, so ask your home insurer directly whether that cover extends to a dog on the Index of Exempted Dogs. Get the answer in writing, because a phone conversation will not help you if a claim is refused.
Which insurers will cover an XL bully's vet bills?
We checked the insurers in our guide to the best pet insurance, plus Everypaw, which published its own XL bully position. This is what each one says today.
| Insurer | New XL bully policies | Existing XL bully policies |
|---|---|---|
| Agria | Yes, lifetime vet fee cover with a Certificate of Exemption. Phone only. No liability cover. | Yes |
| Petplan | No | Still covered "in the same way we always have" |
| Everypaw | No, "even if you have a Certificate of Exemption" | Vet fees honoured. Liability removed at renewal. |
| ManyPets | No. Excludes dogs on the Dangerous Dogs Act list and dogs that look similar. | Excluded |
| Animal Friends | No. Excludes banned breeds and types, crosses included. | Excluded |
| Petgevity | No, "whether exempted or not" | Excluded |
Agria is the only mainstream insurer we found still selling new cover. Its XL bully page says it will offer lifetime vet fee cover as long as you have your Certificate of Exemption, with up to £20,000 a year towards vet bills, renewed in full each year. You cannot get a quote online. You have to call its specialist team on 03330 30 10 00 with your exemption details to hand. Its policy document backs this up: the general exclusion for dogs registered under the Dangerous Dogs Act makes an exception for an XL bully with a valid exemption certificate.
If your dog is already insured with Petplan or Everypaw, think hard before you cancel. Neither will take your dog back once you leave, and any condition your dog has already had would be excluded by a new insurer as pre-existing.
Read the exclusions, even on a policy that accepts your dog
Getting a policy is only half of it. These are the clauses that matter most for an XL bully.
The liability section may not cover the breed. Agria's policy document excludes a list of breeds from its third-party liability section, and the list includes the American Bully and its crosses. That is why Agria says it cannot offer liability cover for an XL bully, even though it covers the dog's vet fees.
Neutering is not covered. Neutering was a condition of the exemption, but Everypaw states that neutering and complications from it are not covered on XL bully policies. Agria's policy document also lists routine castration and spaying among the things it will not pay for.
A history of aggression can rule a dog out. ManyPets, for example, will not insure any dog that has ever been in a fight, been aggressive, or attacked or bitten a person or another animal. Answer every question about your dog's behaviour honestly.
Telling the insurer what your dog is. Everypaw warns that if you take out a policy knowing your dog is an XL bully and do not tell it, it will not pay any claims and will cancel the policy from the start date. The government's definition of an XL bully is based on what a dog looks like, not its paperwork. If your dog could meet that definition, say so when you buy.
A government order is not a vet bill. Agria's policy will not pay for putting a dog to sleep following an order from the government, a council or anyone else with the legal power to make one.
What drives the cost of XL bully insurance
We do not quote prices, because a premium depends on your dog and where you live, and any figure we printed would be wrong for most readers. These are the things that move it:
- Size and weight. Large, heavy dogs cost more to treat, because doses and surgery time scale with body weight. Our XL bully breed page covers the health problems that come with the build, including joint strain, skin problems and heat sensitivity.
- Age. Premiums rise as a dog gets older, and with breeding banned since the end of 2023, every exempted XL bully is now an adult.
- Your postcode. Vet fees vary a lot across the country, and insurers price for it.
- The vet fee limit and excess. A higher annual limit costs more. A higher excess costs less, but you pay it every time you claim.
- Very little competition. With one mainstream insurer selling new policies, you cannot shop around in the usual way. That makes it all the more important to read the policy documents and set the cover level carefully.
If the premium is hard to afford, a higher excess is usually a better way to bring it down than a lower limit, because one expensive claim can use up a low limit in a single year.
A checklist for XL bully owners
- If you are in Scotland and took out liability insurance before 1 July 2026, keep it going until it expires.
- If your dog is insured with Petplan or Everypaw already, keep that policy going unless you have a confirmed alternative.
- If your dog has no vet fee cover, call Agria with your Certificate of Exemption to hand.
- Ask your home insurer, in writing, whether its liability cover includes your dog.
- Answer every question about breed and behaviour honestly, so a claim cannot be refused later.
- Keep to every exemption condition. Insurance will not help with a seized dog.
A basket muzzle your dog is happy to wear makes the public rules much easier to live with, and our guide to muzzle training takes you through it.
Sources
- GOV.UK: ban on XL Bully dogs (last updated 1 October 2026)
- The Dangerous Dogs (Exemption Schemes) (England and Wales) (Amendment) Order 2026
- Scotland: SSI 2026/204 and mygov.scot: insuring your dog
- nidirect: XL Bully dogs
- Dogs Trust: Companion Club changes
- Agria: XL Bully insurance and Agria lifetime dog policy terms and conditions
- Petplan: what you need to know about the American XL Bully ban
- Everypaw: XL Bully information
- ManyPets: are there any breeds you can't insure? and the ManyPets handbook for plans starting or renewing on or after 1 October 2026, from its handbooks page
- Animal Friends: what breeds are excluded?
- Petgevity: excluded breeds
- ABI: insurance payouts for pets top £1 billion for third year in a row (May 2025)
Rules and insurer positions checked on 26 October 2026. Insurers change their policies often, so always read the policy documents before you buy.
Common questions
Do I need insurance for my XL bully?
Not by law any more. Since 1 July 2026, owners of exempted XL bullies in England and Wales no longer need third-party public liability insurance. Northern Ireland dropped the requirement from the same date. Scotland did too, but a policy taken out before 1 July 2026 has to be kept in force until it expires. Insurance is still worth having, both for liability and for vet bills.
Can you insure an XL bully?
Yes, but your choice is narrow. Agria says it will give lifetime vet fee cover to an XL bully with a Certificate of Exemption, and you have to ring its specialist team because quotes are not available online. Petplan and Everypaw keep existing policies going but will not sell new ones. ManyPets, Animal Friends and Petgevity exclude XL bullies, whether the dog is exempted or not.
What is the difference between XL bully liability insurance and health insurance?
Liability insurance pays compensation and legal costs if your dog injures someone or damages their property and you are found legally responsible. Health insurance, which is ordinary pet insurance, pays your dog's own vet bills. They are separate. Agria, for example, will cover an exempted XL bully's vet fees but says it cannot cover third-party liability for the breed.
Where can I get public liability insurance for an XL bully?
It has become hard to find. Dogs Trust removed third-party liability cover from its Companion Club from 1 July 2026, Everypaw removes it from XL bully policies at renewal, and Petplan says it can only offer liability cover for the type in very limited circumstances. Ask your home insurer whether its liability cover includes a dog on the Index of Exempted Dogs, and get the answer in writing.
How much is XL bully insurance?
We do not quote prices, because they depend on your dog and where you live. The things that push the price up are the dog's size and weight, its age, your postcode, the vet fee limit and the excess you choose. With so few insurers willing to quote, there is also very little room to shop around.
Read next
Pets at Home Pet Insurance Review: What the New Policy Really Covers
Our Pets at Home insurance review: lifetime cover up to £15,000 a year, one excess a year, prescription food partly covered, and the breed, age and aggression rules we found in the full policy wording it sent us.
Petgevity Pet Insurance Review: No Forced Co-Payment, Even for Older Dogs
Our Petgevity review: lifetime cover up to £15,000 a year, no compulsory co-payment on Lifetime Plus, declared pre-existing conditions considered, up to eight pets on one policy, and what we found in the policy wording.
Pet Insurance to Avoid? The Big-Name Policies to Think Twice About
Which big-name UK pet insurance policies to think twice about, and what to switch to instead. Time-limited cover from household brands, low lifetime limits, and co-payments that start at 4 or 5, all from the insurers' own documents.